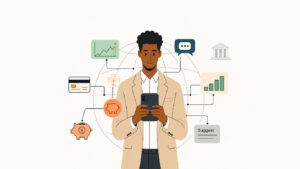
84% of banking customers say they’d switch to a bank that offers timely, relevant financial advice rather than basic transactions. This shift signals a clear truth; access alone is no longer enough. Customers want context, insight, and value.nnImagine a customer checking their balance and instantly seeing savings insights, investment options, or insurance reminders, all personalised and secure. That’s not Open Banking. That’s Open Finance, where connected data creates a unified, intelligent experience across every financial touchpoint.n
From Open Banking to Open Finance
nOpen Banking gave third parties secure access to banking data through APIs. It improved transparency but stayed limited to accounts and payments.nnOpen Finance goes beyond. It connects credit, insurance, pensions, and investments under customer consent, enabling banks to deliver proactive and contextual engagement through digital channels in banking.nnIn emerging markets like India and Southeast Asia, this shift is accelerating. As customers embrace digital retail banking solutions, banks are moving from regulation-led innovation to experience-led transformation, where personalisation defines success.n
Opportunities for the Modern Bank
nBanks still face familiar challenges, siloed data, limited personalisation, and compliance-first digitalisation. Open Finance reframes these issues into opportunities for growth.
By embracing Open Finance, banks can evolve from being service providers to becoming experience enablers, where every interaction deepens trust and engagement.n
Open Finance in Emerging Markets
nAcross Asia, Open Finance is evolving differently than in Europe. While Western markets focus on regulatory frameworks, Asia’s growth is fuelled by innovation and inclusion.nnWith rising smartphone adoption and rapid growth in digital retail banking solutions, banks in India, Vietnam, and the GCC are redefining what financial access means.nnClayfin’s digital channels in banking empower these institutions to bridge formal and informal finance, turning digital engagement into a gateway for financial inclusion.n
The Experience Advantage
nA 2025 global survey found that 17% of consumers are likely to switch financial institutions this year, primarily for better digital experiences. Experience, not access, is now the real differentiator.nnWith Open Finance, banks can turn every data point into a conversation, recommending a credit product when cash flow tightens or suggesting savings boosts based on spending patterns. Through smarter digital channels in banking, data becomes dialogue.n
Clayfin’s Role in the Open Finance Era
nClayfin’s digital retail banking solutions are designed for this new era. Modular, API-driven, and powered by AI-led analytics, Clayfin enables banks to unify data, design contextual journeys, and deliver hyper-personalised digital experiences.nnIn this Open Finance landscape, Clayfin helps financial institutions move beyond transactions, foster deeper relationships and measurable business value.nnThe next phase of banking is about understanding customers. In the Open Finance era, banks that turn transparency into empathy will shape the future of experience.